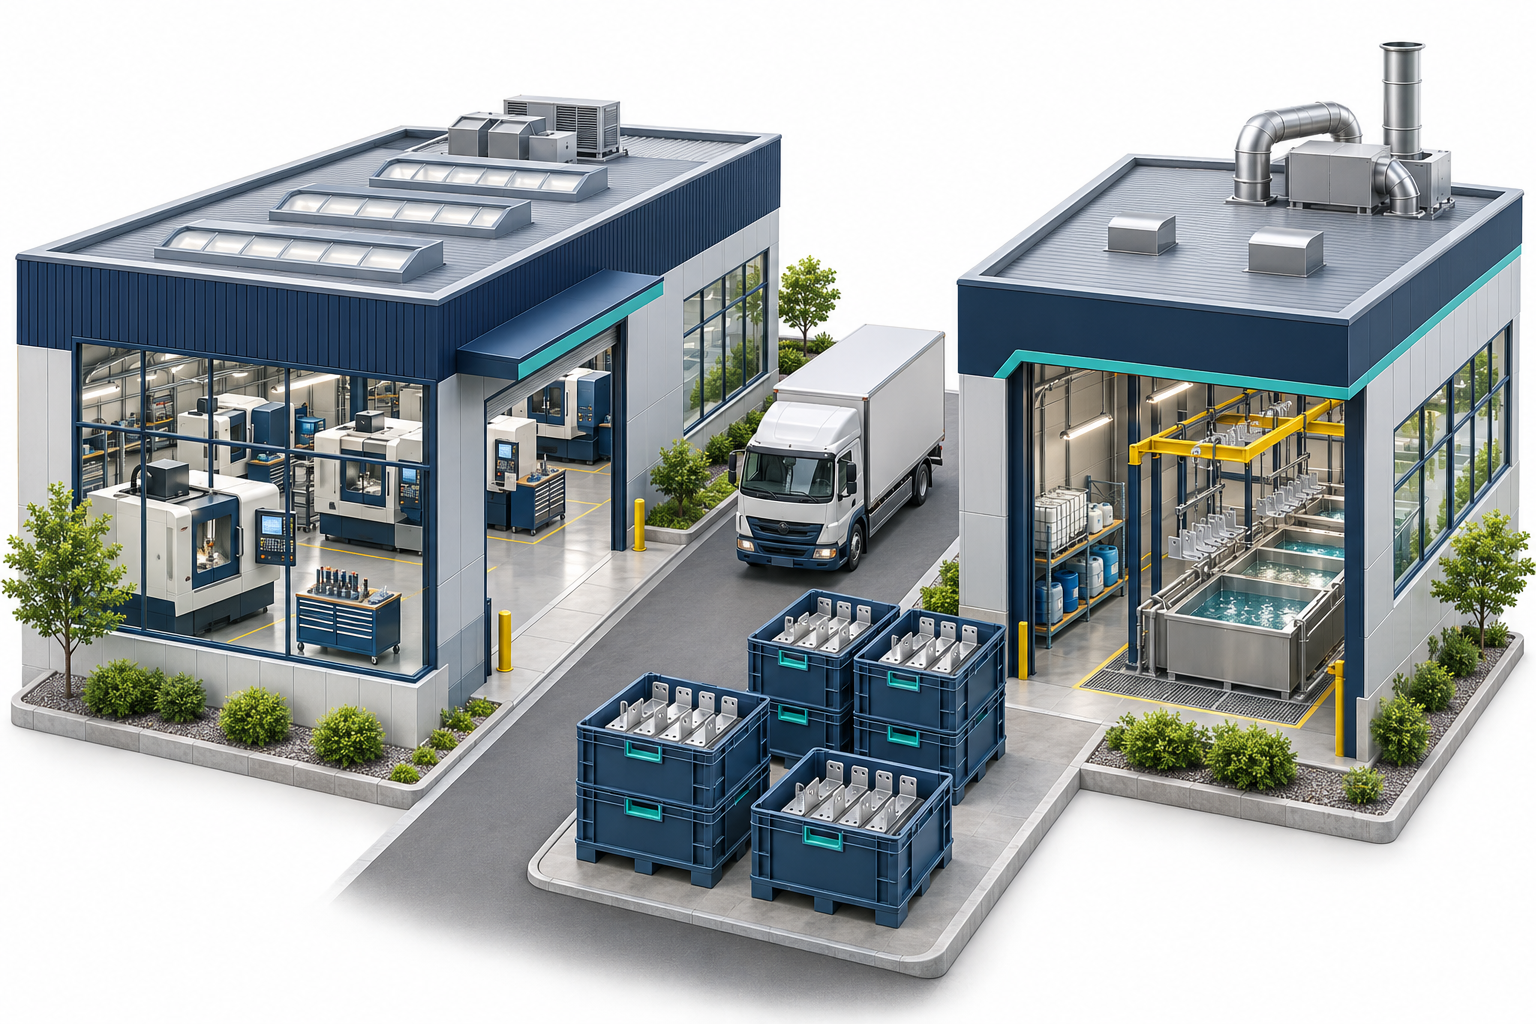
You sent 100 machined brackets to a coating supplier. Sixty came back, five were reported damaged, and the supplier’s invoice refers to a different quantity. Your purchase order tells you what you ordered—but can your team explain where every bracket is?
Subcontract manufacturing ERP should connect the outsourced job, company-owned materials, supplier location, service purchase order and return records. To evaluate that connection, reconcile three things separately: physical quantities, production progress and supplier charges. A purchase order marked received is not, by itself, proof that every part is back or ready to use.
This guide focuses on controlling work outside your factory: machining, plating, heat treatment, coating or outsourced assembly. The checks below are proposed operating controls and evaluation criteria; the ianaiERP section identifies documented behavior and its limits.
What is subcontract manufacturing in an ERP?
Subcontract manufacturing means assigning production work to an outside supplier while retaining a connection to the manufacturing job. You might send a whole assembly for production, outsource one routing operation, or send existing stock for a service.
Start by distinguishing what the vendor does from what materials move. Paying for coating is a service purchase. Sending your brackets to the coating shop is a physical movement. The system must represent both without treating the movement alone as evidence that the service is complete.
| Arrangement | Main control question |
|---|---|
| Whole assembly outsourced | Which components do you supply, which does the vendor supply, and what finished quantity is due? |
| One routing operation outsourced | Which work order and operation are waiting, and what releases the next step? |
| Service on existing stock | Can you identify the exact items or lots sent and returned? |
| Vendor-managed replenishment | Who decides when to replenish stock, rather than who performs a production operation? |
Subcontracting and vendor-managed inventory can coexist, but they describe different responsibilities. Do not use a replenishment agreement as a substitute for production dispatch and return records.
Why must ownership, location and availability stay separate?
For company-owned material, leaving your building does not automatically mean it has been sold or consumed. Establish ownership from the commercial arrangement, then record physical location and operational status independently.
A useful record answers:
- Ownership: Is this your material or material supplied by the subcontractor?
- Location: Is it in your warehouse, in transit, at the supplier or returned?
- Status: Is it awaiting processing, in process, held for inspection, rejected or released?
- Assignment: Which job, order, specification and revision does it belong to?
Do not count material at a supplier as available for immediate picking in your own warehouse. Likewise, do not describe returned material as production-ready until the applicable receiving and quality checks are complete.
Microsoft’s subcontract production documentation illustrates why the model matters: vendor locations, material movements, service purchasing and operation completion are related, while different subcontracting methods handle work in process differently. Those are Dynamics 365 implementation details, not universal instructions for every ERP.
What should travel with a subcontract dispatch?
Create a dispatch record that someone can reconcile without searching through email. The minimum useful detail depends on the work, but this checklist is a practical starting point.
| Record | What to capture | What it helps resolve |
|---|---|---|
| Job reference | Work order, operation, service PO and vendor | Which commitment the shipment supports |
| Product definition | Item, approved drawing or specification, revision | Whether the vendor processed the correct version |
| Quantity | Sent quantity and unit of measure | Pieces versus boxes, weight or service units |
| Traceability | Applicable lot or serial identifiers | Which material was processed and returned |
| Movement | Origin, destination, dispatch date and transport reference | Whether the parts actually left and arrived |
| Service terms | Expected quantity, due date and agreed charging basis | What completion and billing mean |
| Exceptions | Unused material, scrap, rework and return instructions | Who decides what happens to discrepancies |
For an ETO job, attach the approved job-specific specification. For an OEM/ODM order, identify the customer-specific requirement where needed. A vendor name and total quantity are not enough when visually similar parts belong to different revisions.
Record the movement when it occurs. Creating paperwork for a planned shipment should not silently become confirmation that the truck departed.
How do you reconcile a partial return?
Reconcile physical units before closing the service commitment. Separate parts still at the supplier from parts returned, consumed, transferred elsewhere or disposed of with authorization.
For a same-item service with no transformation or unit conversion, a practical check is:
Opening units at vendor + units delivered = units returned + authorized units disposed of + closing units at vendor, adjusted for any other documented movements.
For assembly, cutting or other transformation processes, reconcile each component and output using the relevant BOM, yield and units of measure. Do not compare kilograms of input directly with a count of finished assemblies.
Hypothetical example: 100 brackets sent for coating
The following figures are invented to illustrate a reconciliation, not a customer result or a claim about automatic ERP behavior.
| Physical disposition | Quantity | Evidence or next action |
|---|---|---|
| Returned and accepted | 60 | Match the receipt and inspection record |
| At vendor, processing complete | 25 | Confirm the next shipment |
| At vendor, awaiting rework | 10 | Record the rework decision and due date |
| Authorized scrap, already disposed of | 5 | Retain approval and disposal confirmation |
| Total accounted for | 100 | 60 + 25 + 10 + 5 |
If the five scrapped parts are only awaiting disposal, they are still physically at the supplier and must remain in that balance. “Scrap reported” and “scrap disposed of” are different events.
The 60 accepted units do not automatically settle the supplier invoice. Check whether the agreement charges per attempted unit, accepted unit, batch or another basis. Resolve the service quantity and commercial adjustment separately from the stock count.
AI-generated illustration of a parts check, not an actual customer site.
How should you handle scrap, rejected parts and unused components?
Define the exception process before the first shipment. Otherwise, a “short receipt” can conceal several different situations.
- Unused material: Agree whether it remains for the next job or returns to your plant. Keep it assigned to a known location and identify any reservation.
- Rejected output: Record the inspection decision and whether the material is held, returned for rework or approved for disposal.
- Scrap: Require quantity, reason, traceability where applicable, approval and the agreed disposition.
- Over- or under-delivery: Investigate the unit of measure, packaging count, unrecorded movement and production result before adjusting stock.
- Wrong revision: Isolate the affected material and get an approved disposition rather than changing the reference to make the records agree.
These are controls to design and test. If your ERP does not capture a quality distinction in the subcontract transaction, identify the separate controlled record and how users will find it. An undocumented spreadsheet is not a reliable exception process merely because the core PO is in an ERP.
Where do processing charges belong in the review?
Track the vendor’s processing fee separately from the physical material quantity. Before closing the job, compare the agreed service, receipt quantity, invoice basis and any approved adjustments.
Ask finance and operations to agree on:
- The job or operation receiving the charge.
- Treatment of freight, minimum batch fees, rework and scrap-related charges.
- Timing differences between production completion and the supplier invoice.
- How estimated and actual charges are reconciled.
- Which records establish the cost of the resulting output.
The accounting treatment depends on the workflow, configuration and applicable accounting policy. Avoid assuming that every service invoice follows the same posting path.
What does ianaiERP currently document?
The Subcontract Manufacturing guide describes full outsourcing, ad-hoc services, routing-operation outsourcing and outsourcing a pending whole work order. It distinguishes company-supplied components from vendor-supplied components and describes a vendor-specific location for tracked stock. For work-order jobs, the documented service charge is added as subcontract service overhead to the work order.
The routing-operation guide describes a step staying at the vendor until the full service quantity is received. It also describes bulk dispatch with separate job service lines on a shared purchase order.
Two limits are particularly important when evaluating your workflow. The Receiving Subcontract Work guide states that a partial service receipt leaves the work or stock at the vendor; completion and return occur after full service receipt. It also states that accepted, rejected and scrapped quantities are not recorded separately by the subcontract flow.
If you physically receive split deliveries or require quality disposition by quantity, demonstrate that exact scenario and agree the supported recording procedure before rollout. Do not assume the general reconciliation example above happens automatically in ianaiERP.
Which scenario should you ask an ERP vendor to demonstrate?
Use one real outsourced job, with sensitive details removed if necessary. Ask the demonstrator to complete the entire loop—not just create a subcontract purchase order.
| Test | Evidence to request |
|---|---|
| Dispatch tracked components | Correct item, lot, quantity and supplier location |
| Confirm the outbound movement | Clear distinction between planned and completed dispatch |
| Receive only part of the service | Visible remaining quantity and accurate job state |
| Report rejected output and scrap | Supported records, approval steps and product limitations |
| Return unused components | Linked movement without hiding a consumption variance |
| Complete the remaining work | Correct operation status and physical return records |
| Reconcile the supplier charge | Trace from service line to job cost and invoice |
| Retry after an interrupted return | A way to resolve the exception without duplicate stock |
Treat “we can configure that” as the start of a scoping discussion. Request the actual setup, required custom work and acceptance test.
Start with a vendor-held material review
Choose a recurring review cadence based on volume and risk. List open subcontract jobs, overdue commitments, material at each supplier, unmatched movements and unresolved quality or billing differences. Assign an owner and next action to each exception.
For a first ianaiERP discussion, bring one dispatch, one partial return and one supplier invoice. Request a workflow demonstration that shows how your quantities, operation status and processing charges reconcile—including the exceptions your team handles today.
Documentation and internal links reviewed November 19, 2026. Examples and checklists are editorial operating guidance; verify system behavior against your configuration and agreed implementation scope.